The Corporate Endorsement of Generational Wealth
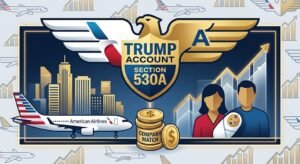
American Airlines announced a major expansion of its family benefits package by committing to match the federal government’s $1,000 seed deposit into newly established “Trump Accounts” for eligible children of its workforce. The decision makes the Fort Worth-based carrier the first major airline to integrate the federal child-savings framework into its corporate compensation structure.
Under the policy, American Airlines will provide a direct, one-time $1,000 company contribution to eligible accounts opened for children born to employees during the statutory eligibility window. When paired with the federal government’s baseline contribution, a qualifying child will start with an immediate $2,000 balance before any personal or familial contributions are made.
The initiative aligns American Airlines with financial giants like Goldman Sachs and Morgan Stanley, expanding the public-private partnership model designed to turn newborn savings accounts into widespread investment vehicles. As legacy corporations look to modernize their benefits packages amid changing labor demographics and complex regulatory environments, American Airlines’ move represents a major intersection of corporate strategy, public policy, and personal finance.
Understanding Trump Accounts: Structure and Mechanics
Formally established under Internal Revenue Code Section 530A, “Trump Accounts” operate as tax-advantaged investment vehicles created for minor children. Designed as long-term compound growth accounts, they blend elements of individual retirement accounts (IRAs) and custodial savings accounts to establish a financial foundation early in life.
+--------------------------------------------------------------------------------+
|                         TRUMP ACCOUNT (530A) OVERVIEW                          |
+--------------------------+-----------------------------------------------------+
| Feature                  | Rule / Specification                                |
+--------------------------+-----------------------------------------------------+
| Account Designation      | IRC Section 530A Tax-Deferred Custodial Account     |
| Federal Seed Funding     | $1,000 one-time deposit from the U.S. Treasury       |
| Federal Seed Eligibility | U.S. citizen children born Jan 1, 2025 - Dec 31, 2028 |
| Annual Contribution Cap  | $5,000 total per year (parents, family, third-party)|
| Pretax Employer Limit    | $2,500 per year (excluded from taxable gross income)|
| Growth Structure         | Tax-deferred compounding until adulthood/withdrawal |
+--------------------------+-----------------------------------------------------+
The Federal Foundation
The core framework of the 530A account grants every qualifying U.S. citizen child born between January 1, 2025, and December 31, 2028, a one-time, non-taxable $1,000 Treasury deposit upon verification of a valid Social Security number. The accounts officially opened nationwide in mid-2026, with roughly 1.4 million children already registered across initial enrollment waves.
The primary policy objective behind 530A accounts is early-stage compound interest. Unlike standard savings vehicles that yield minimal returns or are frequently drawn down for short-term consumption, funds deposited into these accounts are invested in diversified market indices to maximize growth over multi-decade horizons.
Inside American Airlines’ Commitment
American Airlines employs nearly 140,000 workers worldwide, encompassing mainline pilots, flight attendants, mechanics, fleet service clerks, gate agents, and corporate personnel. Because of the airline’s large domestic operational footprint, internal analysts project that thousands of employee dependents will meet the birth-year criteria to claim the company match.
                                   $1,000 Federal Seed
                                           +
                              $1,000 American Airlines Match
                                           =
                             $2,000 Instant Starting Nest Egg
                                           +
                      Optional $2,500/yr Pretax Payroll Contributions
The $1,000 Direct Match
American’s commitment directly mirrors the federal seed. When an eligible employee opens an account for a newborn child born between 2025 and 2028, American Airlines deposits an additional $1,000 directly into the account.
“At American Airlines, our purpose is to care for people on life’s journey, and that includes helping our team members build a strong financial future for themselves and their families,” said CEO Robert Isom in an announcement outlining the program.
The contribution is delivered as an employer-funded benefit, distinct from employee payroll deductions, giving eligible parents an immediate 100% booster on top of the government’s foundation.
Pretax Payroll Contributions Starting in 2027
Alongside the one-time $1,000 match, American Airlines revealed plans to integrate Section 530A contributions directly into its corporate payroll system. Starting in 2027—pending final operational guidelines from the U.S. Department of the Treasury—eligible employees will be permitted to direct up to $2,500 annually in pretax earnings into their children’s accounts.
American estimates that roughly one-third of its total domestic workforce will have immediate access to the pretax payroll deduction option during the initial rollout, creating a seamless, automated mechanism for recurring savings.
The Power of Early Compounding: Modeling the Math
The long-term significance of American Airlines’ match lies in the exponential mechanics of compound interest. In financial markets, time in the market consistently outweighs timing the market, and starting an investment portfolio at birth provides an unmatched compounding timeline.
+-----------------------------------------------------------------------------------+
|               PROJECTED ACCOUNT BALANCES OVER TIME (HYPOTHETICAL)                 |
+-----------------------+---------------------+-------------------+-----------------+
| Investment Scenario   | Value at Age 18     | Value at Age 30   | Value at Age 65 |
+-----------------------+---------------------+-------------------+-----------------+
| $1,000 Govt Seed Only | ~$2,850             | ~$5,740           | ~$43,000        |
| $2,000 Combined Match | ~$5,700             | ~$11,480          | ~$86,000        |
| $2,000 + $1,000/yr    | ~$40,000            | ~$79,000          | ~$590,000       |
| $2,000 + $2,500/yr    | ~$85,000            | ~$168,000         | ~$1,260,000     |
+-----------------------+---------------------+-------------------+-----------------+
*Assumes a constant 6.0% net annualized return compounded annually. Actual returns fluctuate based on portfolio asset allocation and market performance.
If an account receives only the baseline $2,000 ($1,000 federal + $1,000 American Airlines) and no further deposits are ever made, an average annual return of 6.0% grows that nest egg to nearly $5,700 by the child’s 18th birthday. Over a full working lifetime (reaching age 65), that single $2,000 initial grant can compound into over $86,000 without requiring another cent from the family.
When paired with sustained parental contributions via pretax payroll deductions, the results change substantially:
-
Sustained Contributions: A household that deposits the maximum allowable pretax amount of $2,500 annually from birth through age 17 adds $45,000 in principal.
-
Age 18 Balance: Under a conservative 6% annualized market projection, the total accumulation surpasses $85,000 before the child enters the workforce or higher education.
-
Long-Term Multi-Generational Security: If untouched until standard retirement age, the account can exceed $1.2 million, demonstrating how early capital injection acts as a structural hedge against retirement insecurity.
Corporate Momentum and the Public-Private Coalition
American Airlines’ adoption of the Trump Account match is part of a broader shift among major U.S. employers looking to signal family-friendly policies and leverage new federal tax incentives.
               [ U.S. Department of the Treasury (Scott Bessent) ]
                                        |
                 +----------------------+----------------------+
                 |                                             |
        [ Corporate Partners ]                        [ Philanthropic Grants ]
     American Airlines ($1,000 Match)            Michael & Susan Dell Foundation
      Goldman Sachs ($1,000 Match)             ($6.25B pool / $250 per child across
     Morgan Stanley ($1,000 Match)             older birth cohorts 2016–2024)
     50+ Corporate Commitments Total
The Corporate Roster Expands
According to the Treasury Department, more than 50 corporations have formally committed to offering employer contributions or matches for Section 530A accounts. Early adopters were concentrated in investment banking and financial services—including Goldman Sachs and Morgan Stanley—where offering investment matches complements existing executive compensation and wealth advisory products.
Treasury Secretary Scott Bessent highlighted the airline’s participation, stating, “It is encouraging to see our nation’s leading companies, including American Airlines, supporting this effort by offering matching contributions for their employees”.
Philanthropic Amplification
Parallel to corporate payroll matching, private philanthropy has stepped in to backfill gaps in the federal legislation. Because the statutory $1,000 federal seed is strictly restricted to children born between 2025 and 2028, millions of older children are legally ineligible for public seed funds.
To address this cohort, the Michael & Susan Dell Foundation pledged $6.25 billion to disburse $250 direct grants to children born between 2016 and 2024 who reside in ZIP codes with median household incomes below $150,000. The combination of federal seeds, corporate matches from employers like American Airlines, and philanthropic injections is creating an interconnected ecosystem aimed at expanding financial participation across socioeconomic tiers.
Strategic, Economic, and Regulatory Dimensions
Corporate contributions to policy programs are rarely evaluated in a vacuum. American Airlines’ rollout of the $1,000 Trump Account match carries both internal workforce implications and external strategic value.
Regulatory Alignment in Washington
Commercial aviation is among the most heavily regulated sectors in the American economy. Major carriers interact continuously with the Department of Transportation (DOT), the Federal Aviation Administration (FAA), the Department of Justice (DOJ), and congressional committees regarding route allocations, antitrust scrutiny, airspace management, and passenger rights.
Industry analysts note that adopting the administration’s signature savings initiative provides valuable goodwill in Washington at a relatively modest price point.
-
Comparative Cost Structure: In 2018, following the passage of the Tax Cuts and Jobs Act, American Airlines distributed $1,000 bonuses across nearly its entire workforce, costing roughly $130 million.
-
Targeted Expenditure: By comparison, because the Section 530A match applies only to new births within an active four-year window, analysts estimate the actual cash outlay will range between $8 million and $18 million spread over several years.
This allows the airline to publicly champion a headline federal initiative and demonstrate support for the administration while committing a fraction of the capital required for broad wage increases.
+--------------------------------------------------------------------------------+
|                 CORPORATE BENEFIT INITIATIVES: A COST COMPARISON               |
+------------------------------------+------------------+------------------------+
| Initiative                         | Scope of Workers | Total Cost to Carrier  |
+------------------------------------+------------------+------------------------+
| 2018 Tax Reform Bonus              | Across-the-board | ~$130 Million          |
| 2026 Trump Account $1,000 Match    | Newborn Parents  | ~$8 - $18 Million      |
+------------------------------------+------------------+------------------------+
Talent Retention in a Competitive Labor Market
Beyond regulatory signaling, legacy airlines face competition for high-skill labor, particularly in frontline technical operations, dispatch, IT, and maintenance engineering. Family-oriented financial perks provide a differentiator in collective bargaining environments and recruitment pipelines. An employer-sponsored account that visibly funds a child’s financial future can serve as an emotional and practical retention anchor for early-to-mid-career personnel during peak family-planning years.
Practical Realities and Structural Critiques
While the program offers financial benefits to qualifying recipients, financial planners and labor economists note several limitations and trade-offs embedded within the 530A framework.
Narrow Eligibility Windows
The most visible structural limitation is demographic exclusivity. Because both the federal $1,000 seed and American’s corporate match apply strictly to children born between 2025 and 2028, workers whose children were born before 2025 or who have no children receive no direct benefit from the matching capital. This disparity can create minor frictions regarding perceived equity across diverse workforce demographics.
ELIGIBILITY SPECTRUM:
[ Born < 2025 ] -----------> Ineligible for Federal & AA $1,000 Match
[ Born 2025 - 2028 ] ------> Full Eligibility: $1,000 Govt + $1,000 AA Match
[ Born > 2028 ] -----------> Ineligible under current statutory expiration window
Account Rules: 530A vs. 529 College Savings
Employees evaluating the pretax payroll deduction must balance the distinct legal mechanics of Section 530A accounts against traditional alternatives like Section 529 education savings plans or custodial Roth IRAs:
-
Liquidity Constraints: Section 530A accounts are designed for long-term wealth preservation and retirement readiness. Early withdrawals for general consumption before qualifying milestones can trigger penalties and income tax liabilities.
-
Education vs. Wealth Accumulation: Unlike 529 plans, which offer clear state tax exemptions and flexibility for qualified higher-education expenses, 530A accounts prioritize market compounding into early adulthood.
-
Emergency Priorities: For households carrying high-interest consumer debt or lacking six months of emergency liquid reserves, financial advisers emphasize that allocating discretionary income to long-locked custodial accounts may not always take precedence over immediate household balance sheet stability.
The Road Ahead for Public-Private Savings Programs
The formal entry of American Airlines into the Trump Account matching ecosystem signals a broader transition of the 530A initiative from an experimental legislative proposal into standard corporate benefits planning. With Treasury working to finalize employer payroll contribution regulations ahead of 2027, more Fortune 500 companies in manufacturing, retail, and transportation are expected to evaluate similar matching structures.
For American Airlines workers navigating new parenthood between 2025 and 2028, the financial calculation remains straightforward: claiming the combined $2,000 public and corporate grant represents guaranteed seed capital. As participation rates stabilize and account assets begin compounding in institutional index funds, the program will offer a measurable real-world test of whether early, matched capital deposits can transform long-term retirement security for the next generation of American workers.